点击蓝字 · 关注我们
本期主题
Recovery Preferences and the Performance of Leveraged Trading
时 间:2026年10月21日(Wed.)
12:00 - 13:00 p.m.
地 点:同德楼204
主 讲:周航 (上财金融学院)
论文摘要
Investors may prioritize recovering an individual position over the expected financial payoff of their trading strategy. We examine this trade-off using linked orders, executions, and cash flows from retail crypto perpetual futures. Submitted orders reveal attempts to add or exit even when they do not execute. A dynamic model connects additions that make recovery attainable with exits that secure a recovered outcome. We estimate investors’ monetary value of ending without a loss from these choices. Median recovery premiums are about 37 and 54 USDT under two valuation horizons. The preference helps explain exit requests when closing would secure a small net gain. Investors in the highest positive-preference quartile close about 64 percent of position episodes profitably. Yet across the two horizon specifications, only 16–19 percent of these investors earn positive total net profits. Frequent profitable closes can therefore coexist with poor overall performance.
主讲简介
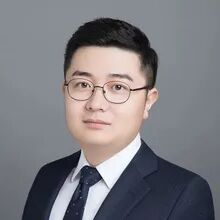
Hang Zhou is an associate professor at the school of finance, SUFE. He works on financial market micro-structure models. He has published papers in leading journals such as Journal of Economic Theory, Economic Theory, Real Estate Economics, Journal of Mathematical Economics and Journal of Economics and Dynamic Control.
欢迎各位老师和同学们前来参加!